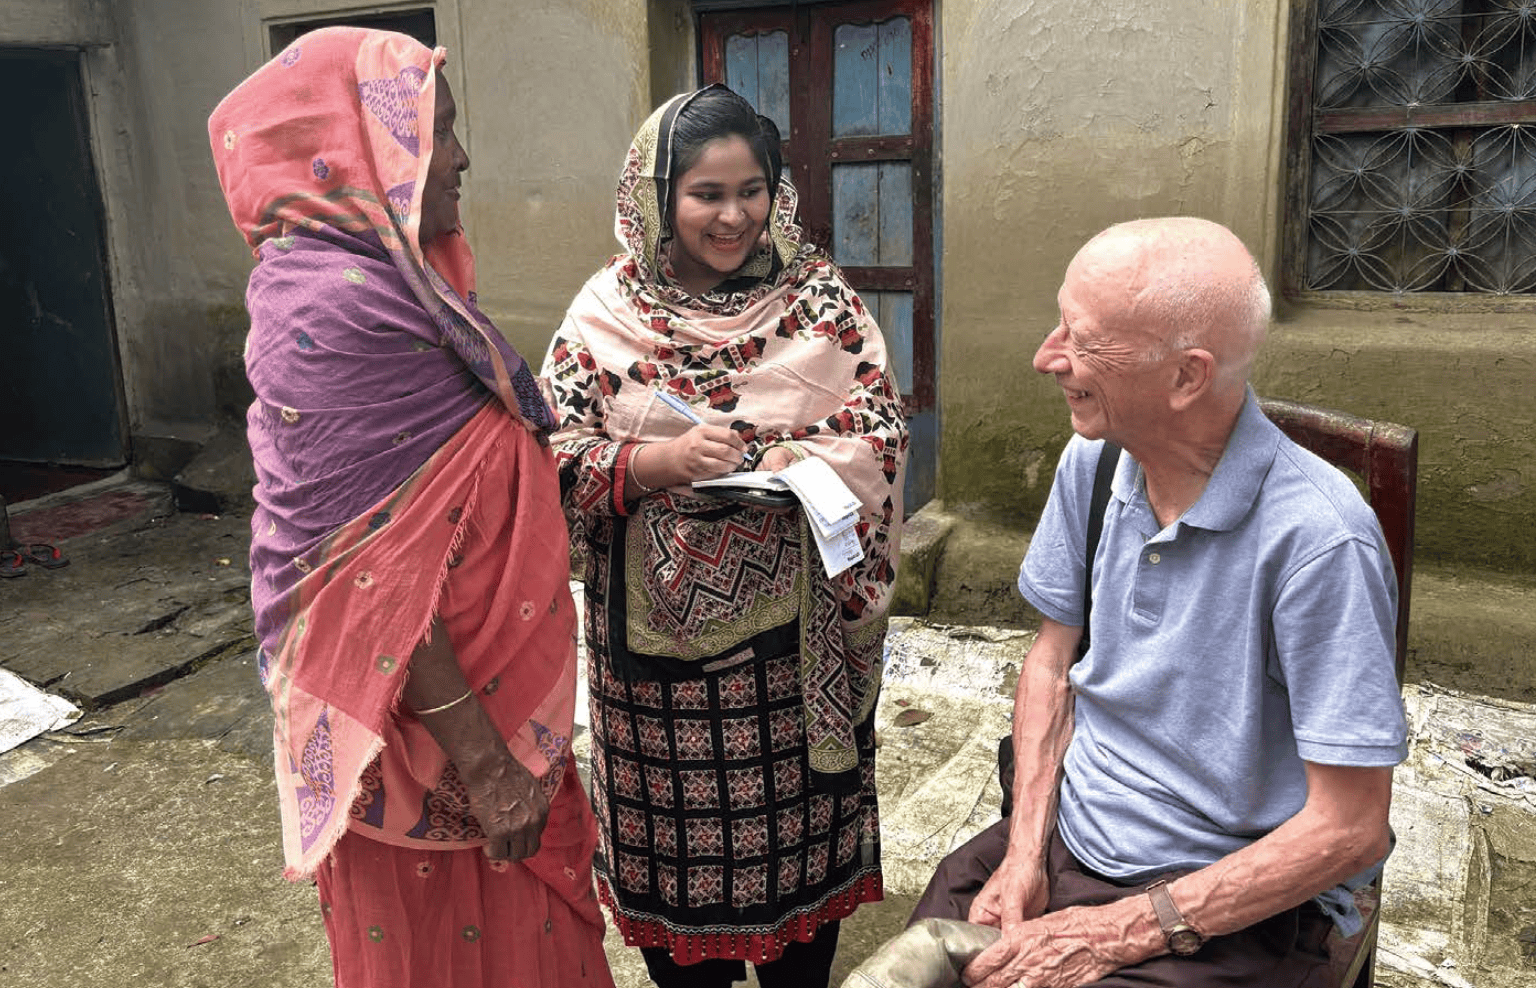
October 28, 2026

Behind the scenes of designing Gojo’s Client Impact Framework

Dear Impact Practitioner,

Have you ever had to quantify the impact your company has on its end clients? Going beyond anecdotal stories, have you had to design a framework and data collection method that lets you speak reliably about the changes, positive and negative, your clients are experiencing?

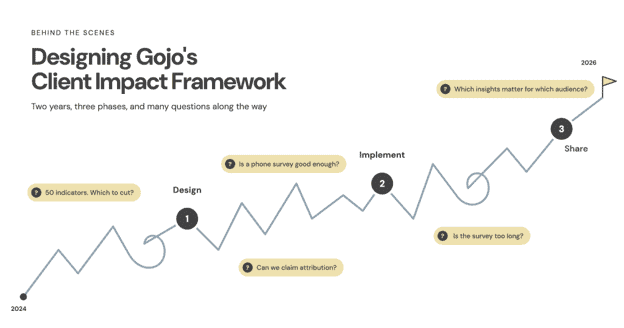
Gojo's impact team was in that spot in 2024. Until then, our impact measurement focused on the outreach (who we serve) and quality (how clients experience our products and services) of our work, through tools like Client Satisfaction and Exit Surveys, with only a light touch on outcomes, the actual changes in clients’ lives. But as an impact team hungry to quantify our impact, we set out to answer: "What is Gojo's impact?" Over the last two years, we developed our own framework and implemented it in five countries.

While designing our framework, I felt like I was walking through uncertain territory, with very few people talking about their challenges and lessons. So today I write this primarily for you, my colleagues on a similar journey, as your impact practitioner next door, candidly sharing my lessons to make your journey a little easier. To make it easier to digest, I've broken the project into three phases, each with its own challenges and lessons:

  1. Design: Defining the framework and methodology
  2. Implement: Running the survey in the field
  3. Share: Analysing the data and reporting to stakeholders

1. Design: Defining the framework and methodology

We began by asking: what have others already done that we can learn from? We spoke to other practitioners and reviewed impact reports and survey tools from the World Bank, CGAP, 60 Decibels, Oikocredit, FINCA and Cerise+SPTF. From this, we built a list of indicators across Outreach, Quality and Outcomes. Our first list had 50 indicators, with 17 of them on outcomes!

"I wish we could learn everything about our clients and how we impacted their lives!" is how I would capture our team's energy at that stage. We listed everything: how clients used their loans, the challenges they faced, their ability to save and cope with emergencies, their confidence managing finances, their optimism about the future, and changes in their meals, education, sanitation and housing.

Curiosity was our best friend at this stage. Although we knew our list was long, we didn't rush to edit ourselves. Since most Outreach and Quality indicators could come from data we already had, we spent the next several months on the outcomes indicators and on designing a data collection methodology from scratch.

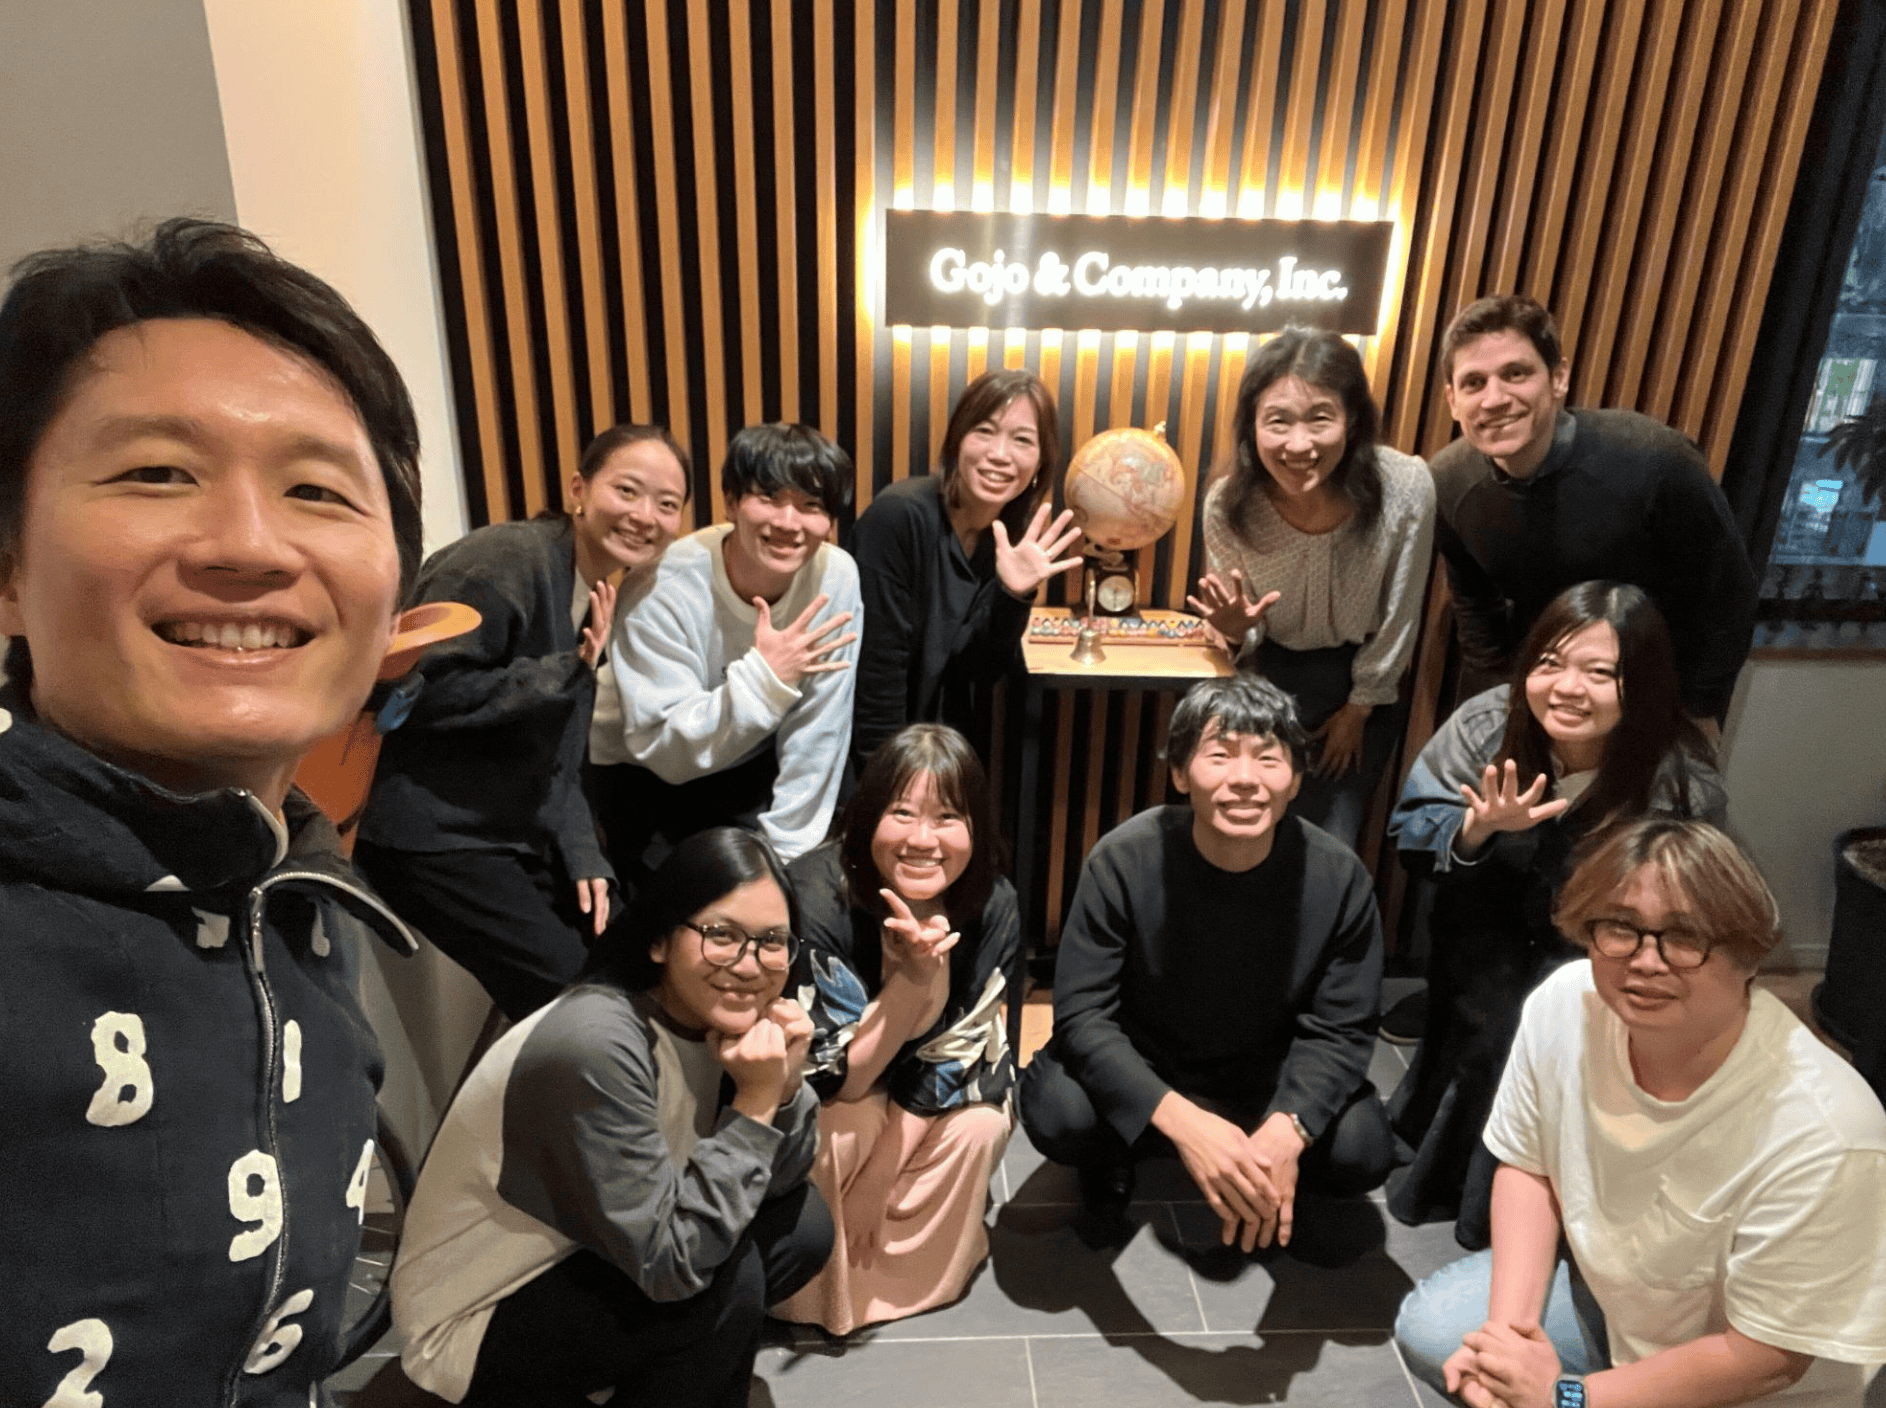
We designed a questionnaire around the indicators and piloted it in Sri Lanka, alongside an internal offsite. First, we got feedback from the Impact and SEPM (Social and Environmental Performance Management) leads of our group companies. They are the champions of social performance, and they know how both their clients and their management think. They helped us see which questions were relevant to their social goals, useful for taking action, easy for clients to understand, and comparable over time. Then a team of five from Gojo split into two groups and interviewed seven clients in person. We wanted to test whether our questions captured what clients were experiencing, and whether clients understood them easily.
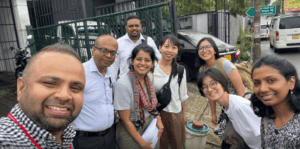
Our pilot team in Sri Lanka


We came back with Version 2 of the questionnaire, now with 11 outcome indicators. But we didn’t stop there. Since the final survey would be run by call centre agents at each group company, we ran a second pilot by phone: the call centre at Sejaya, our group company in Sri Lanka, spoke to 20 clients. We were testing usability. How did the survey feel over the phone? How long did it take? Could we analyse the responses meaningfully? Which questions would we cut?

The answer was clear: our survey was too long. Curiosity is what drives us to search for insights, but left unchecked, it can make outcomes measurement impractical.

So we applied an 80/20 rule. The primary purpose of the survey was to identify actionable insights; the secondary goal was to learn more about clients. That meant 80% of questions had to be relevant, useful and actionable, and only 20% could be nice-to-know. Whether clients could spend on wants or assets, for example, was deprioritised. An overall sense of quality-of-life change was relevant and useful, but detail on sanitation, housing and education was nice-to-know. We also kept the impact survey separate from the Client Satisfaction Survey, to avoid survey fatigue for clients and minimise drop-offs.

With ruthless editing and several debates, we arrived at 8 outcome indicators and 25 indicators in total. The Impact Committee, a sub-committee of Gojo’s Board, gave us the green signal, and we moved on to phases 2 and 3 in 2025.

Throughout this phase, I grappled with two big questions:

  1. Is a telephonic survey with a sample size of 300-400 per company on client outcomes really good enough?
  2. How can we attribute clients' outcomes to our financial products and services?

Both were resolved through conversations with others. Cécile Lapenu from Cerise+SPTF reassured me in one of our catch-ups that outcomes measurement need not be elaborate to be useful. That nudged me towards good-enough measurement over the most perfect or comprehensive one.

Attribution was the tougher dilemma, and Ging Ledesma from Oikocredit inspired me there. At a 2024 Cerise+SPTF panel in the Philippines, someone asked how Oikocredit could claim the impact captured in its "Client Self-perception Survey" as its own. She said that what they capture is the client's self-perception: if a client says Oikocredit impacted them, they take the client's voice at face value.

Our Impact Committee agreed that proving attribution through Randomised Controlled Trials (RCTs), which compare clients against a similar group who didn’t receive the service, would defeat our objective. We wanted lean data that was quick and low-cost to collect, to influence strategic decisions and operational improvements. So instead of trying to prove attribution, we spent our energy on capturing high-quality lean data through rigorous training to minimise bias. We then cross-checked the findings against our group companies’ Management Information System (MIS) data, i.e. their internal client and loan records, or other survey data where available.

2. Implement: Running the survey in the field

With early conviction in our approach, we ran our very first impact survey at five of our majority-owned group companies, in five countries, using the same standardised training for all of them.

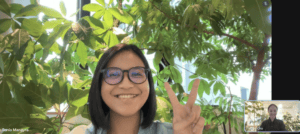
We built a Google Form with a built-in script, so agents could read out exactly what was needed and mark answers as they went. Google Forms was free and already familiar to our group companies. We translated the questionnaire into local languages. We trained the Impact leads, who in turn trained their call centre agents. The agents then practised through role-plays in Google Meet breakout rooms, surveying a fictitious client played by the SEPM lead or a fellow agent.
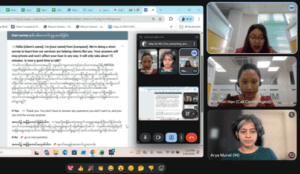
Our online role-play-based training

These sessions demanded a lot of coordination, but they taught us a lot about how questions were received. In Myanmar, we learned that clients are hesitant to share their incomes or debt obligations over the phone, for fear of telephonic scams. This meant accepting ranges or estimates instead of exact numbers, or relying on MIS data. We also learned how daunting “why” questions were: “Why did your income change?” felt much harder for clients to answer than “How did your income change?”

The biggest lesson came from how hard the survey was for agents to fill out. Initially, we required several verbatim answers, with agents typing out clients’ responses word for word. This stretched the survey to 25 minutes. Thankfully, our pilots caught this, and we brought it down to about 15 minutes.

Once again, our unchecked curiosity was running the show! The lesson here was to choose where you need detail and where a standardised five-point scale (say, from “very much decreased” to “very much increased”) will do. Too much detail exhausts clients; too little makes it harder to get the nuance behind their responses.

3. Share: Analysing the data and reporting to stakeholders

With 1,600+ responses in hand, the final phase was cleaning, analysing and reporting. All this data collection is only as good as its analysis and adoption. Our group companies analysed their own data, while Gojo did a portfolio-level analysis across all five companies, segmented by loan type, gender and income level, amongst others. We presented this to Gojo’s Executive Committee and the Impact Committee.

We also presented a one-page summary of each company’s top insights in monthly business review meetings. These focused 15-minute discussions captured CEOs’ attention: some companies identified short-term solutions, while for others, the survey offered a new strategic direction worth considering. Either way, all the CEOs said that the data was a realistic snapshot of their clients’ lives, as they knew them. That was the biggest validation of our efforts.
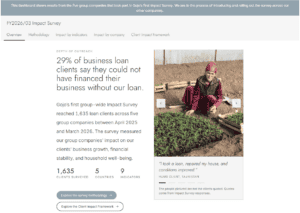
A snapshot of our impact dashboard


Finally, we shared the findings with the rest of the world, including you. We published the numbers in our September 2026 impact report and built an interactive Impact Dashboard. Explore it, and I think you’ll really see the potential of this data. Watch the full webinar here to dive deeper.

In the end, we had at least eight versions of the data analysis, tailored to different stakeholders. That sounds excessive, but each audience needed its own message. As impact professionals, we can easily become married to a single way of presenting our analysis. But to drive adoption, we must see ourselves as storytellers who use data to inspire action in ways that are relevant and interesting to our stakeholders.

–

Looking back, I see how we broke a complex project into manageable phases and focused on one phase at a time. I see how we used design thinking repeatedly, running tiny experiments that kept our curiosity in check and helped us settle for good-enough over perfect. Finally, I see how we took many stakeholders along to the finish line: our immediate team, executive leadership, and the local teams who implemented the survey and acted on its findings.

If you find yourself in any of these phases, I hope you take comfort in knowing that it took us two good years and several iterations to design, measure and share our results. This work takes time and deep thinking, and it is totally normal to not have all the answers. What helps is having the right people around you.

That brings me to my wonderful colleagues: Haruna, Rania, Mayu, Mercy, Cheriel, Mohini, Arisa, all the Impact leads, and Gojo’s Executive Committee and Board members, who each shaped, chiselled and sharpened this framework. Thank you for all your timely support and guidance, without which we would not be here.

Impact measurement is never a destination, but a journey of continuous learning. We have arrived at a milestone, but there are many more discoveries to make, and I will keep sharing my learnings with all of you.

Thanks for staying with me this far. I hope you check out our work and pass on your feedback to me at info@gojo.co. If you feel we can support you in designing your own impact framework, please do reach out!

Your impact practitioner next door,

Arya Murali
Impact Lead, Gojo & Company
 

September 7, 2026

From a Beach in Mar del Plata to Gojo: 27 Years Inside the Microfinance Revolution

I can still picture it. I was lying on the sand in Mar del Plata in January 1996, a few hours south of Buenos Aires, on a break from my first job at BNP Paribas. I was young, I had just started my career, and — like a lot of people at that age — I was turning over the question of what to actually do with my life. Not just a career. A purpose.

A year before, in 1995, I had spent six months in Thailand building one of the country's first internet business — in fact, its first internet service provider. That experience gave me two things at once: a hands-on, visceral sense of just how transformative this new technology could be, and a much deeper understanding of what "emerging country" actually meant — not as an abstraction from a textbook, but as something I had seen and lived. The internet was still new enough, in the mid-1990s, that most people I knew had never used it, but it was clearly spreading, and it was clearly going to change everything. At the same time, poverty felt to me like one of the defining, unresolved problems of the era — visible everywhere I had traveled, and stubbornly resistant to decades of aid. Lying on that beach in Mar del Plata, those two threads came together into a fairly simple thought: what if this new technology, the one that was about to connect the whole world, could also be turned towards closing the gap between the poor and the financial system that had always excluded them?

That thought is the reason this article exists, twenty-seven years later.

1998: joining a movement that barely had a name

I started working on the idea in 1997, while still at BNP Paribas, and in September that year I reached out to Jacques Attali from Buenos Aires with a concept paper. He liked it, and we started exchanging emails and talking it through. Jacques then wrote about the idea for an event at the Aspen Institute, and when we finally met in person in Paris in December 1997, he asked me to turn it into a real business plan. To do that properly, I decided to go and live it rather than write it from behind a desk: I moved to Kenya for six months to turn the business plan into an actual project on the ground. That project became PlaNet Finance, which we formally launched in 1998, initially imagining something like a "virtual bank" that would use the internet to connect microfinance institutions, donors, and technical expertise. Muhammad Yunus, who had founded Grameen Bank in Bangladesh and would later receive the Nobel Peace Prize for it, became not just one of our closest inspirations but the Chairman of our Advisory Board.

It's worth pausing on what "the sector" actually looked like in 1998, because it's almost unrecognizable today. A year earlier, delegates at the first Microcredit Summit in Washington had set what sounded like an almost fantastical goal: reaching 100 million of the world's poorest families with credit by 2005. The baseline they were working from, as of the end of 1997, was 618 institutions worldwide reporting a combined 13.5 million clients, of which 7.6 million were among the poorest of the poor. Microfinance, at that point, was overwhelmingly a world of NGOs and nonprofits: small, mission-driven organizations, often donor-funded, doing extraordinary work on shoestring budgets, largely disconnected from one another and from the formal financial system. There was passion in that world, and real innovation, but there was very little capital, very little technology, and almost no path to reaching more than a tiny fraction of the people who needed these services.

PlaNet Finance's job, in that landscape, was to be connective tissue — bringing technical assistance, ratings, research, and eventually funding to this scattered constellation of NGOs. We grew from two of us in a Paris office to more than 80 people in 30 countries within five years, and by 2008 to nearly 700 people working in almost 80 countries. It was, in many ways, the golden age of "microfinance as an NGO sector" — a period defined by mission-driven expansion, and by a genuine, sometimes naïve, belief that access to a small loan could be transformative on its own.

2005–2018: from NGO to bank

By the mid-2000s, though, something in me had shifted, and something in the sector had shifted too. Technical assistance and advisory work — the classic NGO toolkit — could only go so far. If we wanted to reach not thousands but millions of people, on a sustainable basis, we needed something the NGO model structurally couldn't provide: capital and licenses to grow proper regulated financial institutions.

That's the thinking that led, in 2005, to the creation of MicroCred, built inside PlaNet Finance but designed from day one to be something different — a vehicle to build actual, regulated microfinance institutions, backed by real institutional shareholders: AXA, the European Investment Bank, the International Finance Corporation, alongside PlaNet Finance itself. We issued our first loan in February 2006, to a fruit and vegetable stand in Mexico. Within the year we had launched in Madagascar; the following year, in Sichuan, China, and in Senegal. It doesn't sound dramatic written out like that, but at the time it was a genuinely different bet: that microfinance's future belonged not to donor-funded projects but to institutions built and run like banks — with balance sheets, prudential regulators, and depositors, not just borrowers.

Between 2008 and 2019 I dedicated myself entirely to that bet, building what eventually became a network of microfinance banks across Africa and China. We rebranded as Baobab in 2015 — the tree that survives and gives life in the harshest conditions felt like the right image for what these institutions were doing in frontier markets. By 2019, Baobab was lending a billion dollars a year to a million clients, and had become, by most measures, the leading micro and SME digital bank across its footprint in Africa and China.

Those years also tracked a broader, sometimes painful maturation of the whole sector. Mobile money — M-Pesa above all — showed what digital rails could do for financial inclusion. Compartamos's public listing in Mexico in 2007 forced an uncomfortable but necessary debate about profit and mission in microfinance. The over-indebtedness crisis in Andhra Pradesh in 2010 was a hard lesson about what happens when growth outruns responsible lending and regulation. Out of that decade came a sector that looked completely different from the one I'd joined in 1998: regulated, capitalized, increasingly digital, and judged — rightly — by both its financial and its social performance. By 2010, the sector as a whole had grown from that 1997 baseline of 13.5 million clients to over 200 million — a scale I would never have dared predict when we started PlaNet Finance.

Since 2019: Gojo, the next chapter

When I moved on from Baobab in 2019 to join Gojo & Company as Managing Partner, it felt less like a departure and more like a continuation of the same argument I'd been having with the sector, and with myself, since Mar del Plata.
Joining Gojo also made me feel young again. I recognized in it the same naiveté I had when I created PlaNet Finance — the same enthusiasm to change the world and defeat poverty through microfinance that carried me through the first years of that adventure, between 1999 and 2005. I don't say that as a criticism. That kind of naiveté is often exactly what it takes to convince investors to commit and talented people to join a mission before the proof exists. It has also, inevitably, led Gojo into a few missteps along the way — the kind every young, ambitious organization makes — and those missteps have taught the company a great deal, particularly over the last five years.
Looking back over these 27 years, the arc is clear to me now in a way it never could have been from that beach. Microfinance began as a movement of NGOs proving that the poor were creditworthy and that small loans could change lives. It matured into an industry of regulated, capitalized banks proving that this could be done at real scale and with real accountability. And it is now being accelerated by technology — data, digital channels, and increasingly artificial intelligence — into something that looks less like "microfinance" as a specialized, separate category, and more like ordinary financial services, finally available to everyone.

I don't know exactly what the next chapter looks like, any more than I could have predicted MicroCred while writing PlaNet Finance's first business plan, or Gojo while founding MicroCred. But I do know that the question I asked myself on that beach in Mar del Plata — how do we use the tools of our time to close the gap between the poor and the financial system — is just as urgent today as it was in 1997. It has simply moved into its third act.

Arnaud Ventura

Managing Partner

July 31, 2026

Hrishipara Daily Diaries: The Realities of Overseas Remittances: Cash Flow of Migrant Workers

For the families of migrant workers in developing economies, an overseas remittance is far more than a monthly transaction; it represents a hard-fought lifeline to secure a foothold toward a stable future. Households take on immense economic risks by clearing out family savings, borrowing heavily, and mortgaging property to cover recruitment costs.

This blog post focuses on the most recent 6 months of data (January-June 2026) from the Hrishipara Diaries in Bangladesh, tracking 60 low-income households. Families in Hrishipara regularly send members overseas to seek opportunities in the Middle East (Dubai, Oman, Qatar, and Saudi Arabia) and Southeast Asia (Malaysia, Singapore, and Cambodia), so our diary data offers a look into the financial lives of migrant workers and their support for families back home.

​Delivery Channel: Mobile Finance Dominates

28% of the 60 diarist households recorded at least one overseas remittance over these six months. Collectively, these families received Bangladeshi Taka (“BDT”) 1.97 million (USD 16 thousand)* across 162 remittance transactions.

When we think of international money transfers, we might picture traditional banks or informal cash transfer modes. However, for these very low-income households, the data reveals a modern reality.

*FX rate of the Central Bank of Bangladesh as of the end of June 2026

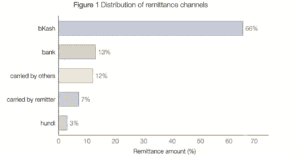
Regulated mobile financial services (MFS) have revolutionized money transfer in the past decade. ‘bKash’ (one of the leading MFS in Bangladesh) is by far the dominant platform among our diarists, processing BDT 1.3 million (USD 11 thousand) of their remittances over the past 6 months, with 82% of receiving households using this mobile digital tool. In contrast, traditional bank transfers accounted for BDT 250,000, serving 24% of the households. Physical carriage, either by the returning remitter or friends/relatives, was used by 52% of households, and the ‘hundi’ (an informal, trust‑based, money transfer network that uses brokers to deliver money anonymously outside the formal banking services) mode accounted for just 3% of the total value.

Cash Flows: Frequency and Festivals

Remitters consider both their families’ household needs and cultural obligations when they make their transfers.

Small but Frequent vs Occasional but Large: Some families rely on a continuous stream of micro-transfers. For instance, Diarist 32 recorded 73 separate, small transfers sent by two sons working overseas and managed locally by their daughters-in-law over the six months. Conversely, others receive infrequent but large lump sums ranging from BDT 10,000 to BDT 100,000 (USD 81 to USD 810) to handle major household expenditures.

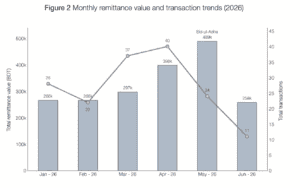
The Festival Surge: Remittances surge in alignment with religious and social calendars. The data shows a spike in May 2026, culminating in a peak of BDT 489,000 (USD 3,961) sent just before the Eid festival. These funds are directed toward family feasts, clothing purchases, and religious rituals.

Remittance Spending: Savings Reinvestment

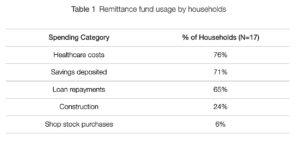
A detailed analysis shows that families tend not to spend on just one major category but distribute lump sums across multiple areas. Below are the top spending patterns for remittance income among our diarists:

Apart from a surge in food costs for almost 100% of households, nearly 71% deposited funds into formal savings and 76% covered healthcare bills. Over 65% immediately repaid loans to MFIs, co-operatives, and other informal lenders (some debts incurred for the migrant's initial visa or travel), indicating that debt clearance is of high priority. Furthermore, 24% of households used remittances for home renovations and 6% for micro-business investments, such as stock purchases.

Impact of Geopolitics

While migration offers a pathway to upward economic mobility, it also increases a household’s exposure to macroeconomic and geopolitical shocks. The escalation of the conflict in Iran in the first half of 2026, leading to rising fuel import costs, intensified domestic economic pressures, pushing the Consumer Price Index (CPI) inflation rate to a high of 9.4% in May. Increasing costs of food, electricity, fuel, and cooking gas squeezed families' purchasing power, even when remittances are received.

For some households, the global pressures directly translate into a crisis. For example, Diarist 20 steadily received funds from her son in Saudi Arabia totaling BDT 145,000 (USD 1,174) between January and April 2026. However, as the Iran conflict heightened, his employer could no longer fund his work permit. To keep him employed, his family back home had to sell farm assets, take out an informal loan, and rely on gifts from relatives to pay for the permit. Another household saw their son return prematurely from Cambodia simply because "there is no work."

Conclusion

It is a common belief that remittance flows among low-income migrant households occur mainly through informal and untracked channels (like ‘hundi’). Still, the financial diaries analysis reveals that a vast majority (66%) of funds are received through regulated financial platforms like bKash. This adoption of digital services has been driven notably by the Government of Bangladesh's cash incentive on formal inward remittances, which was introduced in 2019 and increased to 2.5% in 2022.

Furthermore, the behavioral pattern of these households is cultural and event-driven, as seen in the surge in remittances in May, coinciding with the Eid festivities. These overseas remittances not only uplift a single family but also have a broader, indirect impact on extended families, local communities, and financial institutions as funds are directed into savings, loan repayments, small business and self-employment activities. Given this digital adoption, predictable surge patterns, and vulnerability to geopolitical shocks, how can formal financial providers design savings or insurance products that align with these seasonal remittance cycles?

Mercyline Manoj

Researcher-in-Residence

May 27, 2026

Working at Gojo

Hello, my name is Fumiyo Cho from the Gojo IR team. I joined Gojo last July, but my first encounter with the company actually goes back ten years.
In the summer of my first year of university, I participated in the International Development Planning Contest — a program aimed to solve social issues in developing countries through business. Before a week-long fieldwork trip to Indonesia, we held a preparatory retreat in Tokyo where we had the opportunity to hear from various guest speakers. One of them was Gojo's founder, Taejun. I learned about the potential of microfinance to expand people's choices, and about Gojo's seemingly boundless ambition to be a private-sector World Bank. As someone whose own choices were once limited by where and how I was born, I strongly resonated with Gojo's vision, and began to think that I wanted to work someday at Gojo — or at a company creating similar social impact.
Since startups like Gojo often don't hire new graduates, and wanting to build my own foundation first, I spent four and a half years in the Global Markets division of a foreign investment bank, followed by about a year at a Japanese real estate developer. It was at that point that the opportunity arose, and I joined Gojo last July as an IR Officer. I'd like to share what I've actually experienced working here.


Both of my previous workplaces greatly emphasise in-person communication, with frequent client dinners and internal social events. So when I first joined Gojo, I was thrown off by a reality where more than half the team was overseas and even Tokyo-based members worked mostly from home. I felt anxious about how to build relationships with colleagues. With so many members in child-rearing stages of life, after-work dinners were rare too — and I remember worrying that this might be a very dry, transactional organisation, and wondering what would happen if I couldn't fit in. Those concerns turned out to be unfounded, and today I work at Gojo feeling fully myself — thanks, I believe, to Gojo's distinctive culture and the thoughtful ways it's been built.
On the topic of remote work: since online meetings are the norm, the only chances to meet overseas colleagues in person are through business trips or offsites, which can feel isolating. But at the Monthly Member Meeting (a company-wide meeting held each month, known as the MMM), new members get a full 30 minutes to introduce themselves using slides — sharing everything from childhood to the present, including a motivation graph. That session became a natural starting point for exchanging messages and scheduling catch-up calls with colleagues. Since everyone's slides remain accessible at any time, it also helps deepen mutual understanding. I think this is what ensures psychological safety even in a text-and-video-first environment, and keeps relationships from feeling cold or distant. The MMM also gives everyone a chance to see each other's faces, hear updates from teams I don't usually interact with, and sometimes break out into smaller group discussions — all of which helps build genuine understanding of members across the company.
Another reason for our sense of unity, I think, is that there are deliberate structures in place to help each member stay connected to their life mission  and the company’s mission. In our quarterly company-wide Guiding Principles sessions, we discuss topics that tend to spark disagreement and that many of us rarely get to talk about in everyday Japanese social settings, such as: "What do you think about the fact that people in developed countries working on developing-world issues earn far more than those working in those countries?" The question of what it means to work at Gojo, and what we owe to our clients, is also reinforced regularly through the weekly management meeting (open for all members to observe) and through day-to-day conversations. I feel genuinely fortunate to be moving forward together with teammates who share the same purpose.

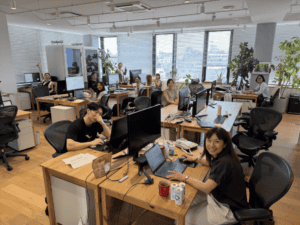
More than anything, though, it is the diversity of the environment that allows me to bring my whole self to work here. Gojo's office near Kitasando is neither large nor fancy — the number of houseplants far outnumbers the people. Since most members work from home, on any given day without a special event, only a handful of people are in. Yet the space is warmly decorated with photos of clients taken during Taejun's visits to our group companies, and with handicrafts from the countries where those companies operate. The atmosphere is wonderfully homey — perhaps a little too homey: I was genuinely surprised, when I first joined, to see a colleague working cross-legged on the sofa with their shoes off. Taejun himself is in the office almost every day, even if only briefly — and he's the type to embrace freedom even at work. He's been known to join Executive Committee meetings while air-drumming or grinding coffee beans, and we've even had an independent director join a Board meeting from a beautiful garden in Spain. At my previous workplaces, any of this would have been absolutely unthinkable, and I probably would have judged it harshly through my old lens. But I quickly came to understand that it wasn't a lack of seriousness — the meetings are genuinely intense and substantive. The Gojo culture is: if you're doing what needs to be done and delivering results, the form doesn't matter. And I think it's precisely that freedom that makes it completely natural to have a colleague join a meeting while holding their baby — and that enables each of us, even amid busy days, to hold onto our personal lives and continue working in ways that reflect our own diverse choices.

Generating social impact while sustaining profitability, and achieving Gojo's mission, is anything but easy. But I hope to keep moving forward, step by step, together with my teammates.

In the meeting room of our plant-filled office

A day when more members than usual came into the office

On a business trip to India with a France-based colleague

Fumiyo Cho

IR Officer, Gojo & Company, Inc.

April 30, 2026

A Shopkeeper’s Survival: Why don’t high sales always mean high profit?

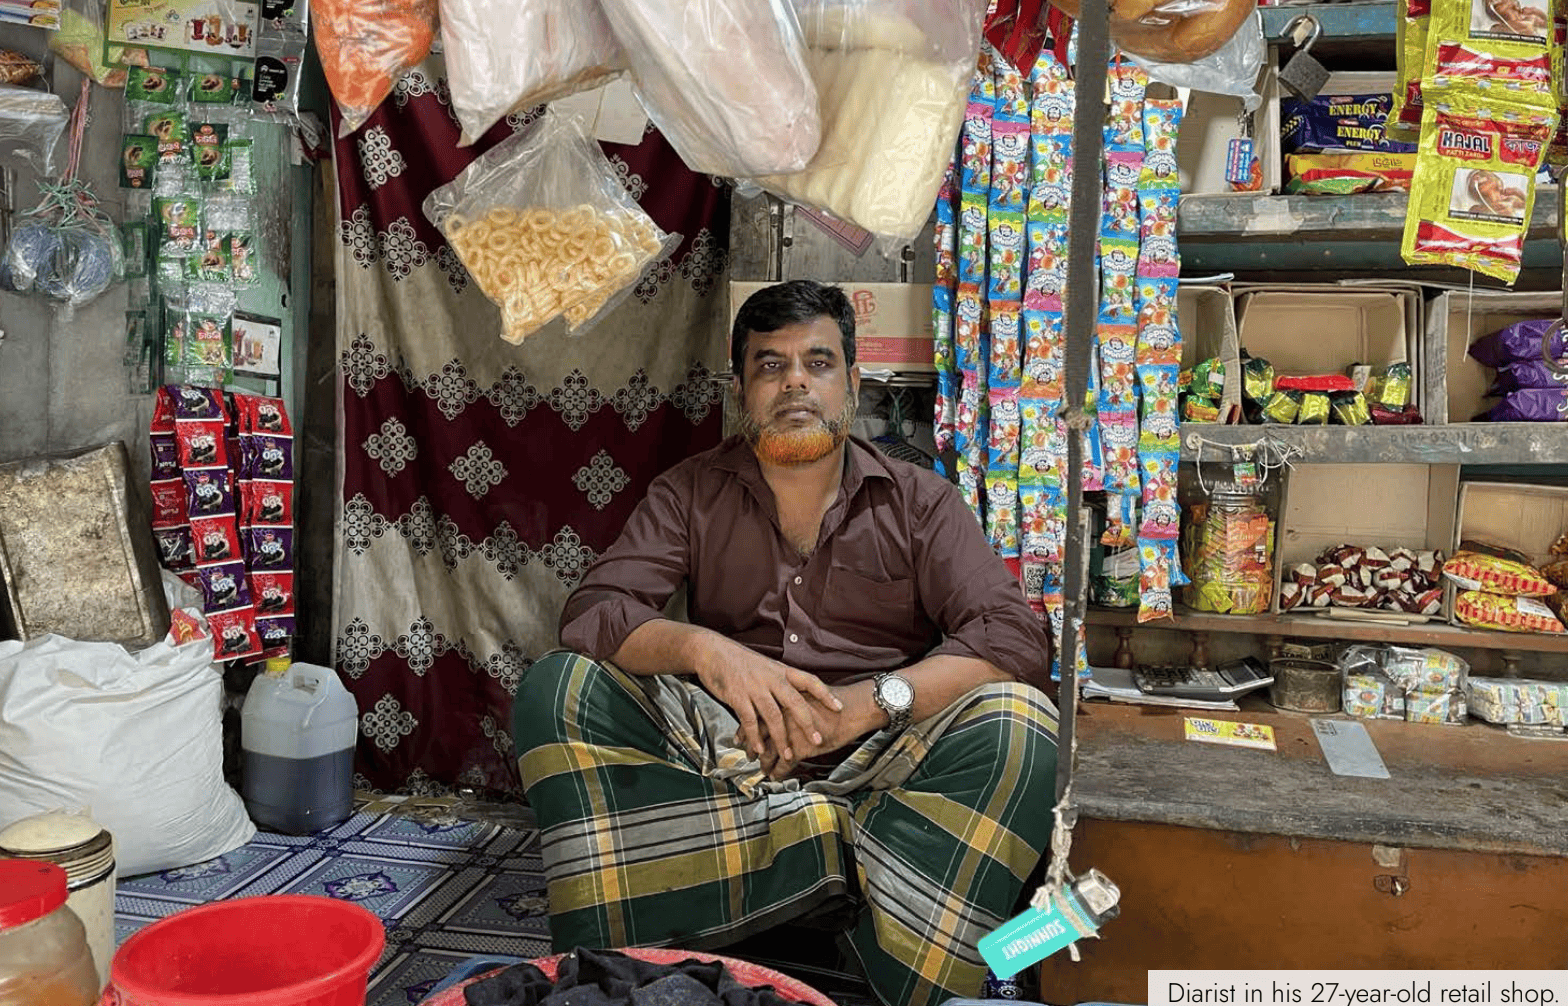
In the outskirts of Kapasia, 58-year-old Aamir (name changed) lives with  his wife, mother, and two children. A participant in Hrishipara daily diaries  research since 2015, Aamir holds a secondary school certificate (Grade 10)  and was inspired by his mother to open his own retail shop. His daily records  offer a window into how a micro-entrepreneur balances the pressures of daily  survival and long-term asset building.


Household Earnings

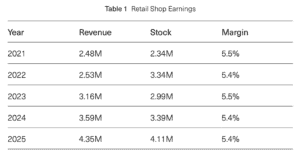
Aamir’s shop earned a cumulative revenue of BDT 17.7 million over the past  five years. Although this figure seems impressive, the analysis of his daily  business operations reveals constant liquidity pressure. Each morning, he  invests 8,000-12,000 Taka in buying stock, which almost covers his average  daily sales of 10,000 Taka. This daily capital reinvestment leaves a thin profit  margin, just enough to sustain his household needs while keeping his shop  running. To further illustrate his business financials, the following table shows  the total revenue and stock purchases over 5 years.

From 2021 to 2025, revenue grew from BDT 2.48 million to BDT 4.35 million,  a 75% increase. However, profitability did not improve as stock purchases  increased proportionally, leaving the profit margin at 5.4%-5.5%.

To maintain the household’s financial stability, Aamir’s mother engaged in  livestock farming and sold them during festive seasons. The livestock sales  generated a substantial 187% gross margin and a net profit of BDT 105,000,  though such returns were infrequent. The resulting paradox was notable; while  the retail shop accounted for 99% of total revenue, it yielded low margins;  conversely, livestock farming offered high profitability but lacked the volume  and consistency of the shop.


"Baki" (Shop Credit)

Another key finding from the qualitative interview is the prevalence of ‘baki’, a  system where customers buy groceries on credit and pay in installments. This  practice created a significant financial burden for Aamir. His outstanding ‘baki’  has now reached nearly BDT 100,000. He keeps a record and hopes to recover  most of it, but some is unrecoverable as customers have migrated out of the  area. With a tight 5% profit margin, he has reduced the amount of shop credit  he gives over time, as it affects both his business and household stability.  


Household Consumption

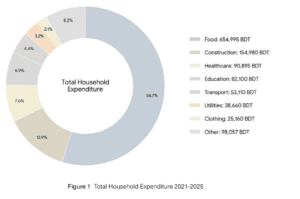
Amid business pressures, household consumption patterns stayed consistent.  Among non-business expenses, food (54.7%) accounted for the largest share  of total household spending, followed by construction, health care, and  education. Monthly cash flow fell short at times, especially when inventory  purchases or payment cycles exceeded sales revenue.


Regular Savings

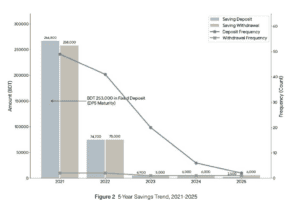
Aamir regularly saved in a Deposit Pension Scheme (DPS) at a commercial  bank and a co-operative bank. His DPS matured into a significant lump sum  in 2021, which he reinvested into a fixed deposit. However, over the last five  years, his liquid savings have considerably decreased due to rising household  expenses, including the medical costs of his father’s terminal illness and his  children’s education.  Figure 2 depicts five years of savings deposits and withdrawals, with transaction amounts shown as bars and frequencies as lines. 


"Howlat" (Interest—Free Loans)

Aamir is cautious with debt. Over the last five years, Aamir’s total borrowing  was BDT 250,000, equal to just 1.4% of his total revenue. This sum comprised  two loans from a close relative: BDT 150,000 in September 2022 and  BDT 100,000 in March 2023. Both loans were secured through “howlat”, a  community-based, interest-free lending built on social relationships and trust.  

Despite the high availability of microfinance loans in Bangladesh, Aamir  avoided them, fearing that his thin profit margins and rising household costs  would make repayments difficult to manage. He preferred informal loans  over institutional ones, as they offered greater repayment flexibility. Notably,  he never used debt for consumption and invested all borrowed funds in  building long-term assets, such as buying property, renovating his house, and  expanding his shop. 


Conclusion

Aamir’s journey highlights the struggle to sustain a micro business amid  market competition and rising household needs. Despite a 75% increase in  revenue, his profit margins remained stagnant, highlighting a stark contrast  between sales growth and profitability. Rising stock costs and the burden of  ‘baki’ (shop credit) drained his liquidity; consequently, his high sales figures did  not bring the financial ease due to tight cash flow. 

In the midst of these challenges, Aamir manages his limited resources with  care. To stabilize income, he leverages livestock sales, turns savings into  secure fixed deposits, and uses ‘howlats’ (informal, interest-free loans). Even  when family needs outpaced his retail earnings over the years, he maintained  minimal withdrawals from his savings. His ability to buy land and expand  his shop despite these constraints demonstrates his resilience in building  household assets.  

Aamir’s story makes it evident that meaningful growth for micro-businesses  takes a long time to materialize; yet, it is the small choices, such as income  diversification, affordable debt, and consistent saving, that ensure their survival.  To move beyond mere survival, shopkeepers like Aamir could transition from  the limitations of daily, cash-dependent buying to the more efficient bulk stock  procurement. Such an approach, whether using informal or formal loans, would  significantly reduce procurement costs and enable retailers to break the cycle of  daily purchases, converting high sales volumes into sustainable profit margins.

written by Mercyline

March 27, 2026

How One Woman’s Choice Can Create Change

I started working as an intern at Gojo, drawn by its work in promoting financial inclusion and its impact on women’s empowerment. This month, through a separate opportunity, I joined a two-week exchange programme at a women’s university in Bangladesh. The university was established to provide higher education opportunities not only to women in Bangladesh, but also to those from socially disadvantaged backgrounds across Asia and the Middle East. During this programme, I met a friend whose story made me reflect deeply on the power of women’s economic independence and the potential of education. In this blog, I would like to share her story.


Narges is a 20-year-old woman from Afghanistan. Due to the Taliban regime, women are not allowed to attend university in her home country, so she left her family and came to Bangladesh to continue her education, even under life-threatening circumstances. 

What she shared with me was the story of her family. Her mother married at a very young age and has since been financially dependent on her husband, with no income of her own. In such relationships, the balance of power is often heavily skewed—if a wife does not comply, her access to money can be restricted, and even in situations of violence, leaving or speaking up becomes extremely difficult. For her mother, this was simply “normal.” 

However, Narges’ sisters chose a different path. Both of them were married at a very young age—at 14 and 15—and were themselves victims of child marriage. Despite the significant social expectations and challenges that came with it, they made the decision to continue their education. Through learning, they came to understand the importance of financial independence and chose to keep working even after marriage, despite not being understood at first. By earning their own income, they gained the ability to support themselves and speak up when needed. Financial independence, in this sense, is not only about earning money—it is about having the power to make choices in one’s own life.

For Narges, her sisters became role models. Watching them, she realised that women also have power, and she studied hard from a young age, eventually deciding to pursue higher education even if it meant leaving her country. This influence gradually transformed her entire family—her mother, who once accepted dependency as natural, now places the highest importance on her daughters’ education and strongly believes in women’s economic independence. One woman’s choice can change the values of a family and expand the possibilities for the next generation. Listening to this story made me reflect again on the meaning of financial inclusion, which Gojo works to promote. It is not simply about access to money, but about enabling those in vulnerable positions, especially women, to gain the power to choose their own lives. And this change does not end with one individual. When one woman becomes independent, the impact spreads to her family, friends, and community. As more women like Narges’ sisters emerge, values begin to shift, and the accumulation of these micro-level changes leads to broader change.

Through this experience, I truly felt that chain of change. At the same time, I was deeply struck by the power of sharing stories. Narges told me she feels both responsibility and pride in telling her story and her sisters’ story, because they may inspire other women. As an intern at Gojo, being exposed to these real voices has helped me understand the meaning of financial inclusion in a much more tangible way. Small changes begin with one person’s choice, and those changes continue to reach others. I believe it is this accumulation that ultimately has the power to change society.

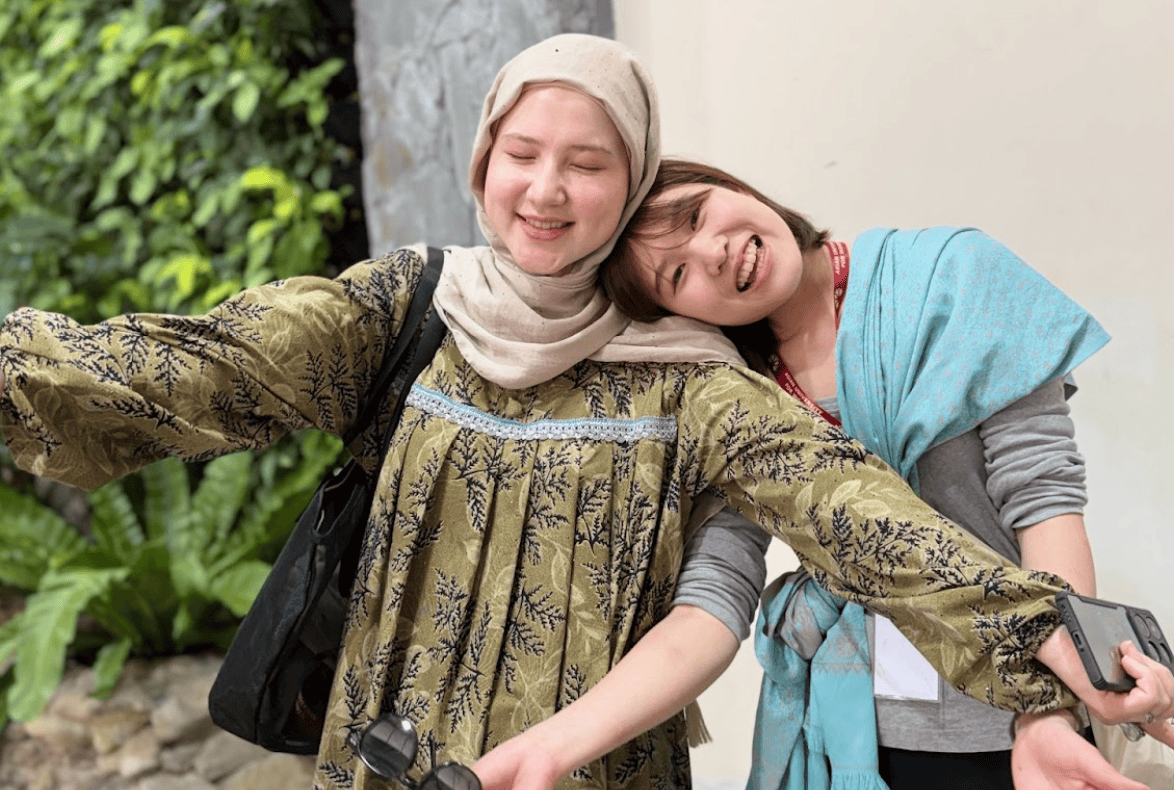
Narges (center) with friends after sharing her story in an International Women’s Day event / Aki Hoshino

Aki Hoshino
Corporate Planning Intern

February 26, 2026

How Gojo Achieved D&I AWARD Over Years

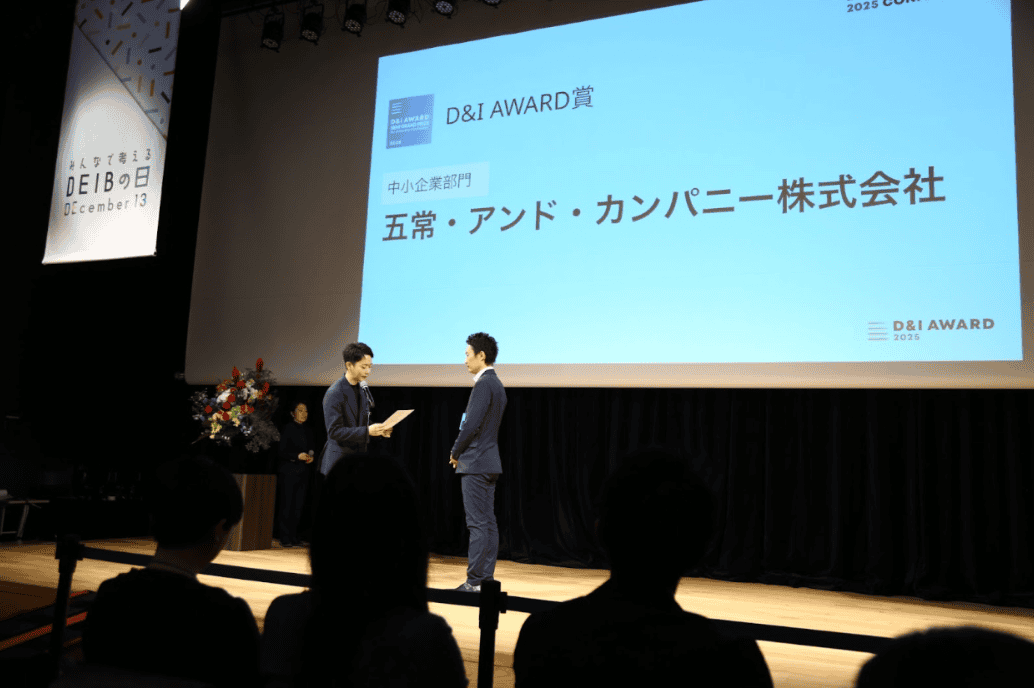
I am thrilled to share that Gojo recently received the Semi-Grand Prize for diversity and inclusion in the SME Category at the D&I AWARD. The D&I AWARD is Japan's largest certification for companies working on diversity and inclusion, designed to make D&I a societal "norm." Receiving this recognition is a significant milestone for us, especially as we have grown into a diverse team with members from over ten different countries.

A few years ago, I wrote about how diversity builds better workplaces, drawing from my early career experiences navigating homogeneous local offices versus intentionally inclusive international organisations. Since stepping into the role of Chief People & Inclusion Officer at Gojo, my goal has been to build an environment where everyone can thrive without the pressure to conform to a single "majority" norm.

When the award secretariat evaluated our efforts, they highlighted our commitment to a highly transparent and flat organisational culture. At Gojo, our board and management's strong commitment shapes our culture. To promote transparency, almost all internal documents and meetings are accessible to everyone. I want to share three concrete ways we are actively building a truly diverse and inclusive organisation:

  • Achieving Gender Equality through Board-Level KPIs: Gender diversity is a critical topic in Japan, and we believe it requires deliberate action and measurable goals. In March 2021, our Nomination Committee officially set a quantitative Diversity Target. Back then, the female ratio among Gojo members was only 36%, and we had just one female member on our Board of Directors. It took time, but having a concrete, board-level commitment with quantitative KPIs fundamentally drove our decisions across hiring and promotions. Today, I am proud to share that we have achieved a 50% female ratio among our members, and we now have three female board members out of nine. We have intentionally built this diverse board by welcoming international female talent to join as Outside Directors, such as Royanne Doi, Almira Zejnilagic, and Kshama Fernandes.
  • Overcome Cultural Conflict with "Culture Mapping": Having a diverse team brings diverse perspectives, but it also brings different communication styles. We noticed that during management meetings, direct debate styles could feel overwhelming to members from cultures that traditionally do not debate so actively. To address this, we implemented a "Culture Mapping" workshop. By visualising how different cultures approach decision-making and feedback, we fostered mutual understanding and reduced friction.
  • Fostering Empathy through the "Happiness Chart": We believe D&I is about understanding individual differences, not just gender or nationality. New members joining Gojo present a "Happiness Chart," sharing the highs and lows of their personal life journeys. Sharing vulnerability creates cross-cultural empathy; it turns out that no matter where you grew up, the struggle of a major life transition or the awkwardness of your teenage years looks surprisingly similar on a line graph. Finding these shared emotional experiences builds profound psychological safety and a comfortable workplace.

While we are honoured by the Semi-Grand Prize, we know there is still much work to do. We are actively working on long-term challenges, such as deliberately creating opportunities from the middle-management level to continually improve gender diversity in the top management team. We are also expanding our mental wellness support systems to enhance psychological safety and focusing on sharing our D&I knowledge with our group companies overseas to create a broader social impact.

Ultimately, our goal in driving these initiatives is to create a work environment where everyone feels psychological safety. As part of my ongoing dedication to our members' growth, I am currently becoming a certified coach of Co-Active coaching. I have been providing coaching to my colleagues to help them understand their core leadership qualities and truly unleash their full potential.

We can never say D&I has been achieved; it is a continuous journey to build a better organisation for everyone.

Takao Takahashi
Chief People & Inclusion Officer, Gojo & Company, Inc.

January 29, 2026

Hrishipara Daily Diaries-Diarist Sultana: What Drives Financial Well-Being?

Introduction

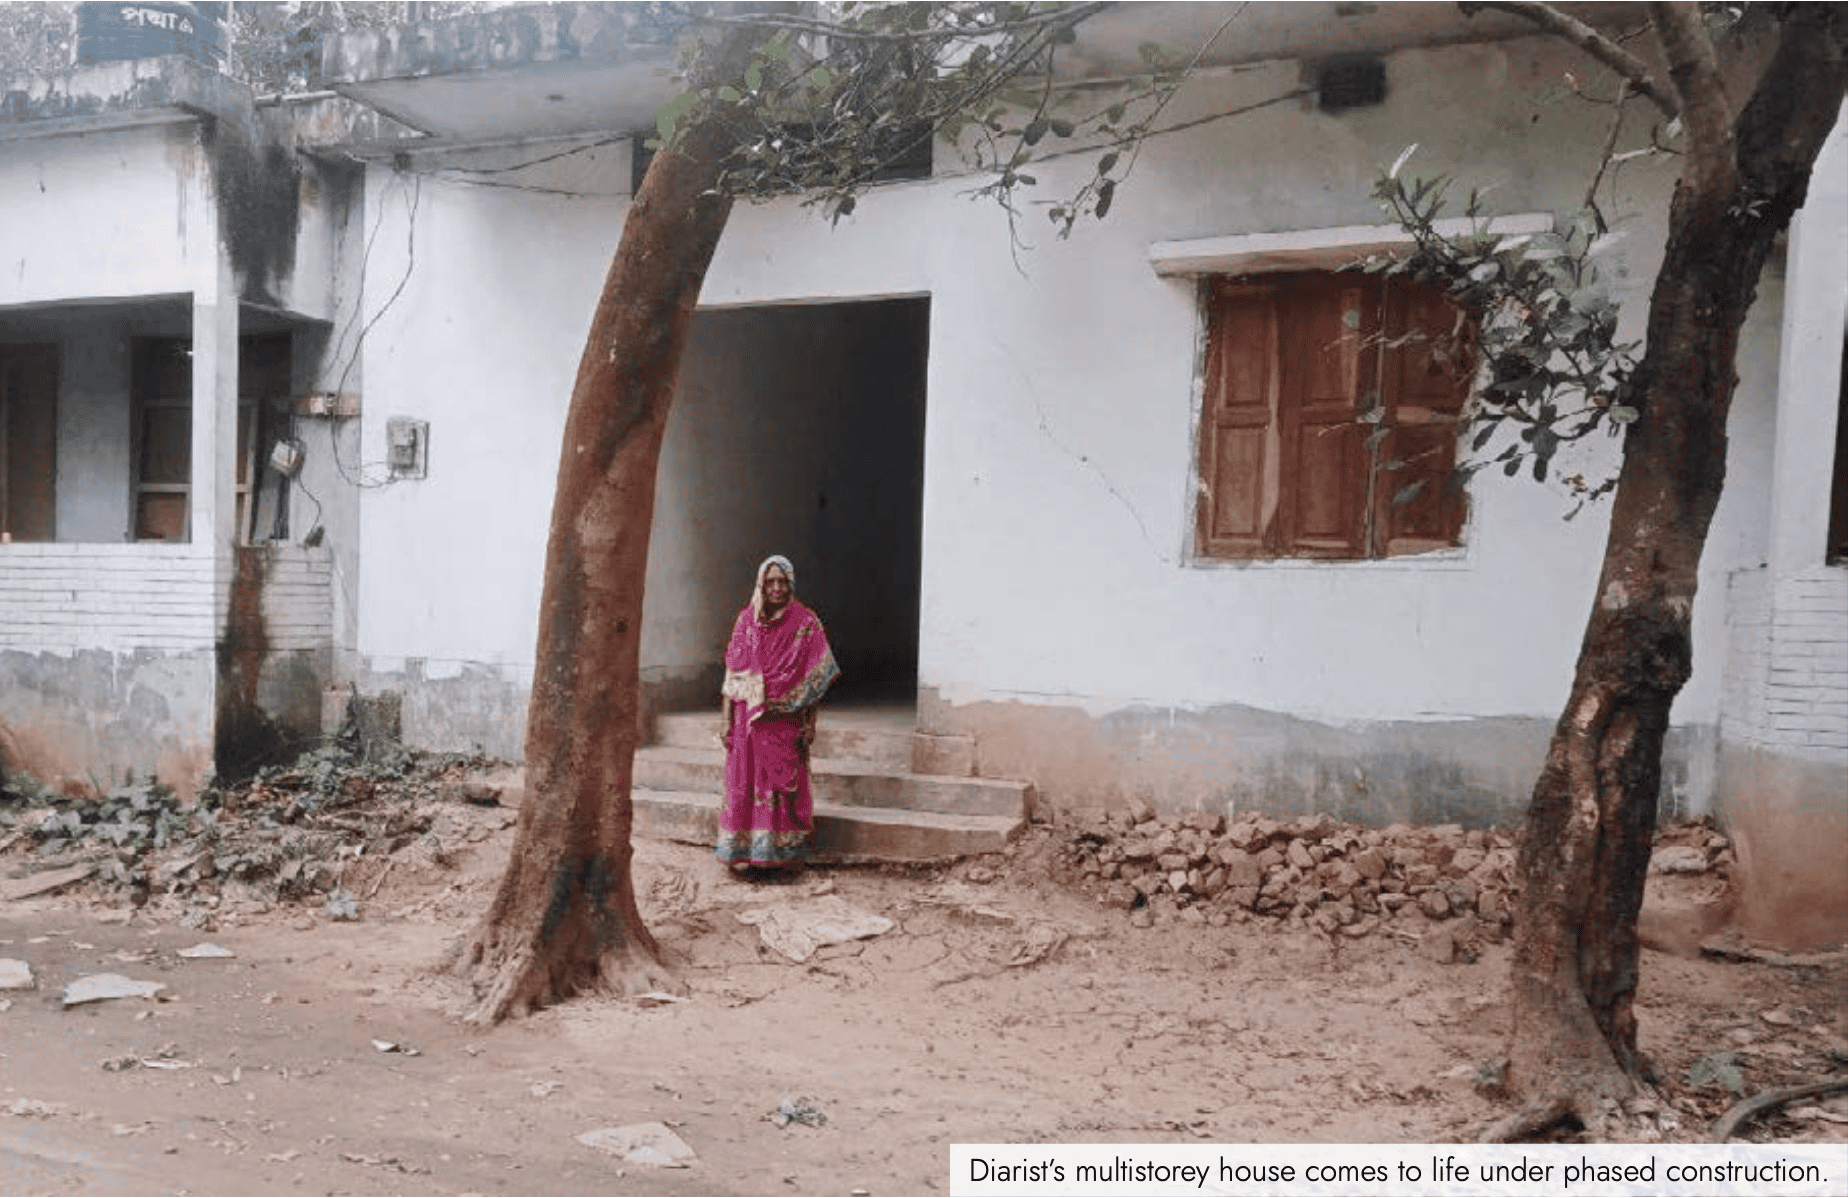
In the village of Hrishipara, Bangladesh, lives 76-year-old Sultana (name changed). To a general observer, she appears to be an elderly grandmother living on a rural homestead. But to the Hrishipara Daily Diaries Project (HDDP) team, she is a woman who effectively used credit, micro-savings, and prudence to build a life of self-sufficiency. 

Sultana has been a diarist with the HDDP since 2015. Her journey was never easy. She was educated up to class 8 and married a relative. Her husband deserted her early in the marriage, leaving her to raise three children alone. In rural low-income households, this is a sure ingredient for long-term poverty. However, Sultana possessed a relentless work ethic. Refusing to succumb to despair, she raised her children by husking paddy and rearing livestock, saving every ‘Taka’ she could earn.

Strategic Debt

In 1986, she made a decision that would change the financial path of her life: she started taking loans from the Grameen Bank. Over the next four decades, she didn't just borrow; she used Grameen’s suite of products. She took multiple loans and top-ups;  her early loans were for capital investments, such as purchasing livestock and housing loans for land acquisition and house construction. Figure 1 below presents a consolidated view of her annual debt cycle and repayments, highlighting her remarkable ability to pay off loans.

As observed in Figure 1, Sultana demonstrates exceptional debt clearance. The data shows high repayment volumes and consistent debt closure, with repayments often structured on a weekly and monthly basis. Notably, towards the end of 2025, she is primarily debt-free.

She used borrowing to generate income and build assets, and eventually leveraged credit to finance her sons' overseas migration, a calculated investment that would pay dividends later.

Aggressive Savings

While many see loans as the primary tool for growth, Sultana not only utilised loans but also understood that savings are the actual engine of wealth. She became a disciplined contributor to Grameen Bank’s savings products, such as the Grameen Pension Savings (GPS) and Fixed Deposit scheme, which doubled every seven years in the early years. In addition, she saved in Shohoz Shonchoy* (Easy Savings, co-operative), a daily savings model for low-income households led by Stuart Rutherford (Director of HDDP).

In earlier years, her deposits were modest: 1,000 Taka per month for GPS, 150–200 Taka in Grameen’s general savings account, and 20–40 Taka daily in Easy Savings.  However, her consistency was key.  When her sons began sending remittances from abroad, she diligently repaid her loans and fully saved the remaining funds. When her savings matured after 10 years at GPS, she reinvested them in Grameen’s fixed deposit schemes, which doubled in value over time. She treated every Taka held as a brick in the foundation of her future.

Dream House

Sultana’s most significant "investments" were in her children. Using her savings and loans, she sent both sons, and later her grandson, overseas for work. For 12 years, her eldest son sent remittances via Agrani Bank, while her younger son used bKash, Bangladesh’s leading Mobile Financial Services (MFS) company. Sultana managed these funds with precision. She cleared her loans, maintained her savings, and in 2018, began her ultimate project: replacing her mud house with a concrete home.

Sultana shared the pictures of her house plan during our visit. Her vision was a three-storey building where her entire family, with children and grandchildren, could live together. Remarkably, she spent 1,700,000 Taka just to lay the foundations, primarily from her savings. She has built multiple rooms and finished one storey of her house as of 2025.

Conclusion

Today, at 76, Sultana is far from "retired." She now works as a babysitter and diligently continues to save her earnings. When we asked the simple question, "Why do you still save?" her response was poignant: "I want to put away for the future... I don't want to be a burden if I fall ill."

Sultana lives alone as her sons work outside Hrishipara. She understands that as their families grow, resources will stretch. Yet, she looks forward, currently helping her son process a visa for overseas travel and dreaming of the day her three-storey home is finally complete. She even occasionally supports her estranged husband’s medical needs.

Among other diarists, Sultana stands out as a resilient figure in the project. She grew her earnings into a formidable sum by taking on strategic debt to build assets and by maintaining reinvestment habits. Through micro-savings and the use of suitable financial products, she changed a position of vulnerability into independence.


*Shohoz Shonchoy (Easy Savings) started in 2002, is an ultra-flexible microfinance organisation for poor and very poor people, focusing on savings but also offering loans with no fixed repayment schedule, no fixed repayment period, and no requirement to join a group. It aims to serve rather than make a profit, but has generated a surplus over time.

Written by Mercyline Manoj

November 27, 2025

Hrishipara Daily Diaries-Diarist Rasiya: Can Social Programmes Make a Difference?

“Ma… Daima…”, that’s how the villagers and children affectionately call her. At 80 years old, Rasiya (name changed for privacy) is one of Hrishipara’s respected elders, a birth assistant whose life reflects dedication, skill, and resilience.

The Gojo Impact Team visited Hrishipara village in Bangladesh to meet participants of the Hrishipara Daily Diaries project, led by Director Stuart Rutherford and Manager Kalim Ullah. The team conducted in-depth interviews to better understand household livelihoods and financial practices among long-term diarists.

Rasiya has been part of the diaries project since 2017. A divorced grandmother, she has raised five sons and continues to care for and support her family even today. For nearly three decades, she has worked as a midwife, providing vital assistance to women during childbirth in and around Hrishipara.

Skill to livelihood

Her journey as a trained birth assistant began in 2002, when UNICEF and BRAC launched joint community health and social programmes in the Gazipur District. As part of their neonatal and childbirth initiatives, a few women from the area were selected and trained by medical professionals at a local clinic, and Rasiya (by then already more than 50 years old and long experienced in traditional midwifery) was among them.

Since then, she has worked with the same clinic for over 23 years, providing care for expectant mothers. She can interpret sonographic images, identify fetal positions, and assess whether a normal delivery is possible or whether the patient should be referred to a city hospital. Rasiya remains on call 24/7, assisting with births at any hour. Her income comes primarily from clinic payments, supplemented by small tips from grateful families after successful deliveries.

Modest Earnings

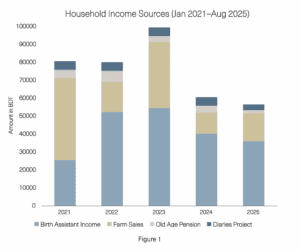
Rasiya’s household income ranges between BDT 60,000 and 97,000 (approximately USD 490–974) annually, reflecting both seasonal and livelihood fluctuations. While her work as a birth assistant accounts for the core of her earnings, she also owns livestock, has farm sales, and sells milk to supplement her income. In emergencies, she sells livestock to raise quick cash, using these proceeds as a liquidity buffer. She is particularly fond of raising goats.

Additionally, she receives a government old-age pension, which provides a small but steady financial safety net. Her income is supplemented by occasional cash gifts sent during EID festivals by her sons, who reside in Singapore and Qatar. These funds are transferred through bKash (a leading Mobile Financial Service provider in Bangladesh, launched in 2011, which has become the largest mobile wallet system in the country, offering services to a large segment of rural households), and collected from local mobile agents. On average, her monthly income stands around BDT 6,000 (approximately USD 49), a modest but diversified livelihood typical of older women in rural Bangladesh.

Figure 1 below depicts a sample of Rasiya’s monthly inflows over a 5-year research period.

Managing Expenditures

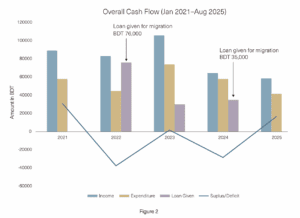
Rasiya manages her finances carefully, using core earnings to cover essential expenses such as food, utilities, healthcare, and household needs. Although she generally spends within her means, financial diaries data reveal annual deficits in 2022 and 2024, as shown in Figure 2.

These deficits resulted mainly from howlats (interest-free loans) Rasiya gave to family members. In 2022, she extended howlats totaling BDT 76,000, and in 2024, another BDT 35,000, primarily to her sons and grandsons to support their overseas migration. To fulfill their travel, Rasiya sold livestock and used her savings to meet family expectations.

Rasiya’s decisions reflect the strong culture of familial responsibility in rural Bangladesh, where older adults support younger relatives’ aspirations despite personal financial strain. They also show that livelihood security for women like Rasiya is closely tied to family dynamics and the willingness to support family well-being.

Figure 2 compares her overall income and expenditure over the five-year period from 2021 to 2025.

Conclusion

Rasiya’s story captures the economic reality of a few elderly rural women: modest incomes sustained by skill, reputation, and social trust built over years. Targeted social programmes can make a difference, and the training she received through the UNICEF–BRAC initiatives continues to benefit her and her community today.

Her income, while steady, remains vulnerable to shocks. Yet her resourcefulness and energy is remarkable. By maintaining multiple income sources, such as birth assistance, livestock rearing, and a government pension, she manages to live independently while continuing to support pregnant women in her community.

Rasiya’s experience highlights the importance of ongoing mentoring and institutional support for community health workers like her. For microfinance institutions, there is an opportunity to complement training programmes with micro-savings and health financing tools to help workers manage emergencies without liquidating assets. Medical institutions, in turn, should consider expanding stipends or incentives for health workers to formalise and stabilise their roles.

Together, government agencies, NGOs, and microfinance institutions can build a holistic ecosystem where financial inclusion and social empowerment go hand in hand, ensuring that stories like Rasiya’s are not rare exceptions.

Written by Mercyline Manoj

September 30, 2025

A Family Story from Tajikistan

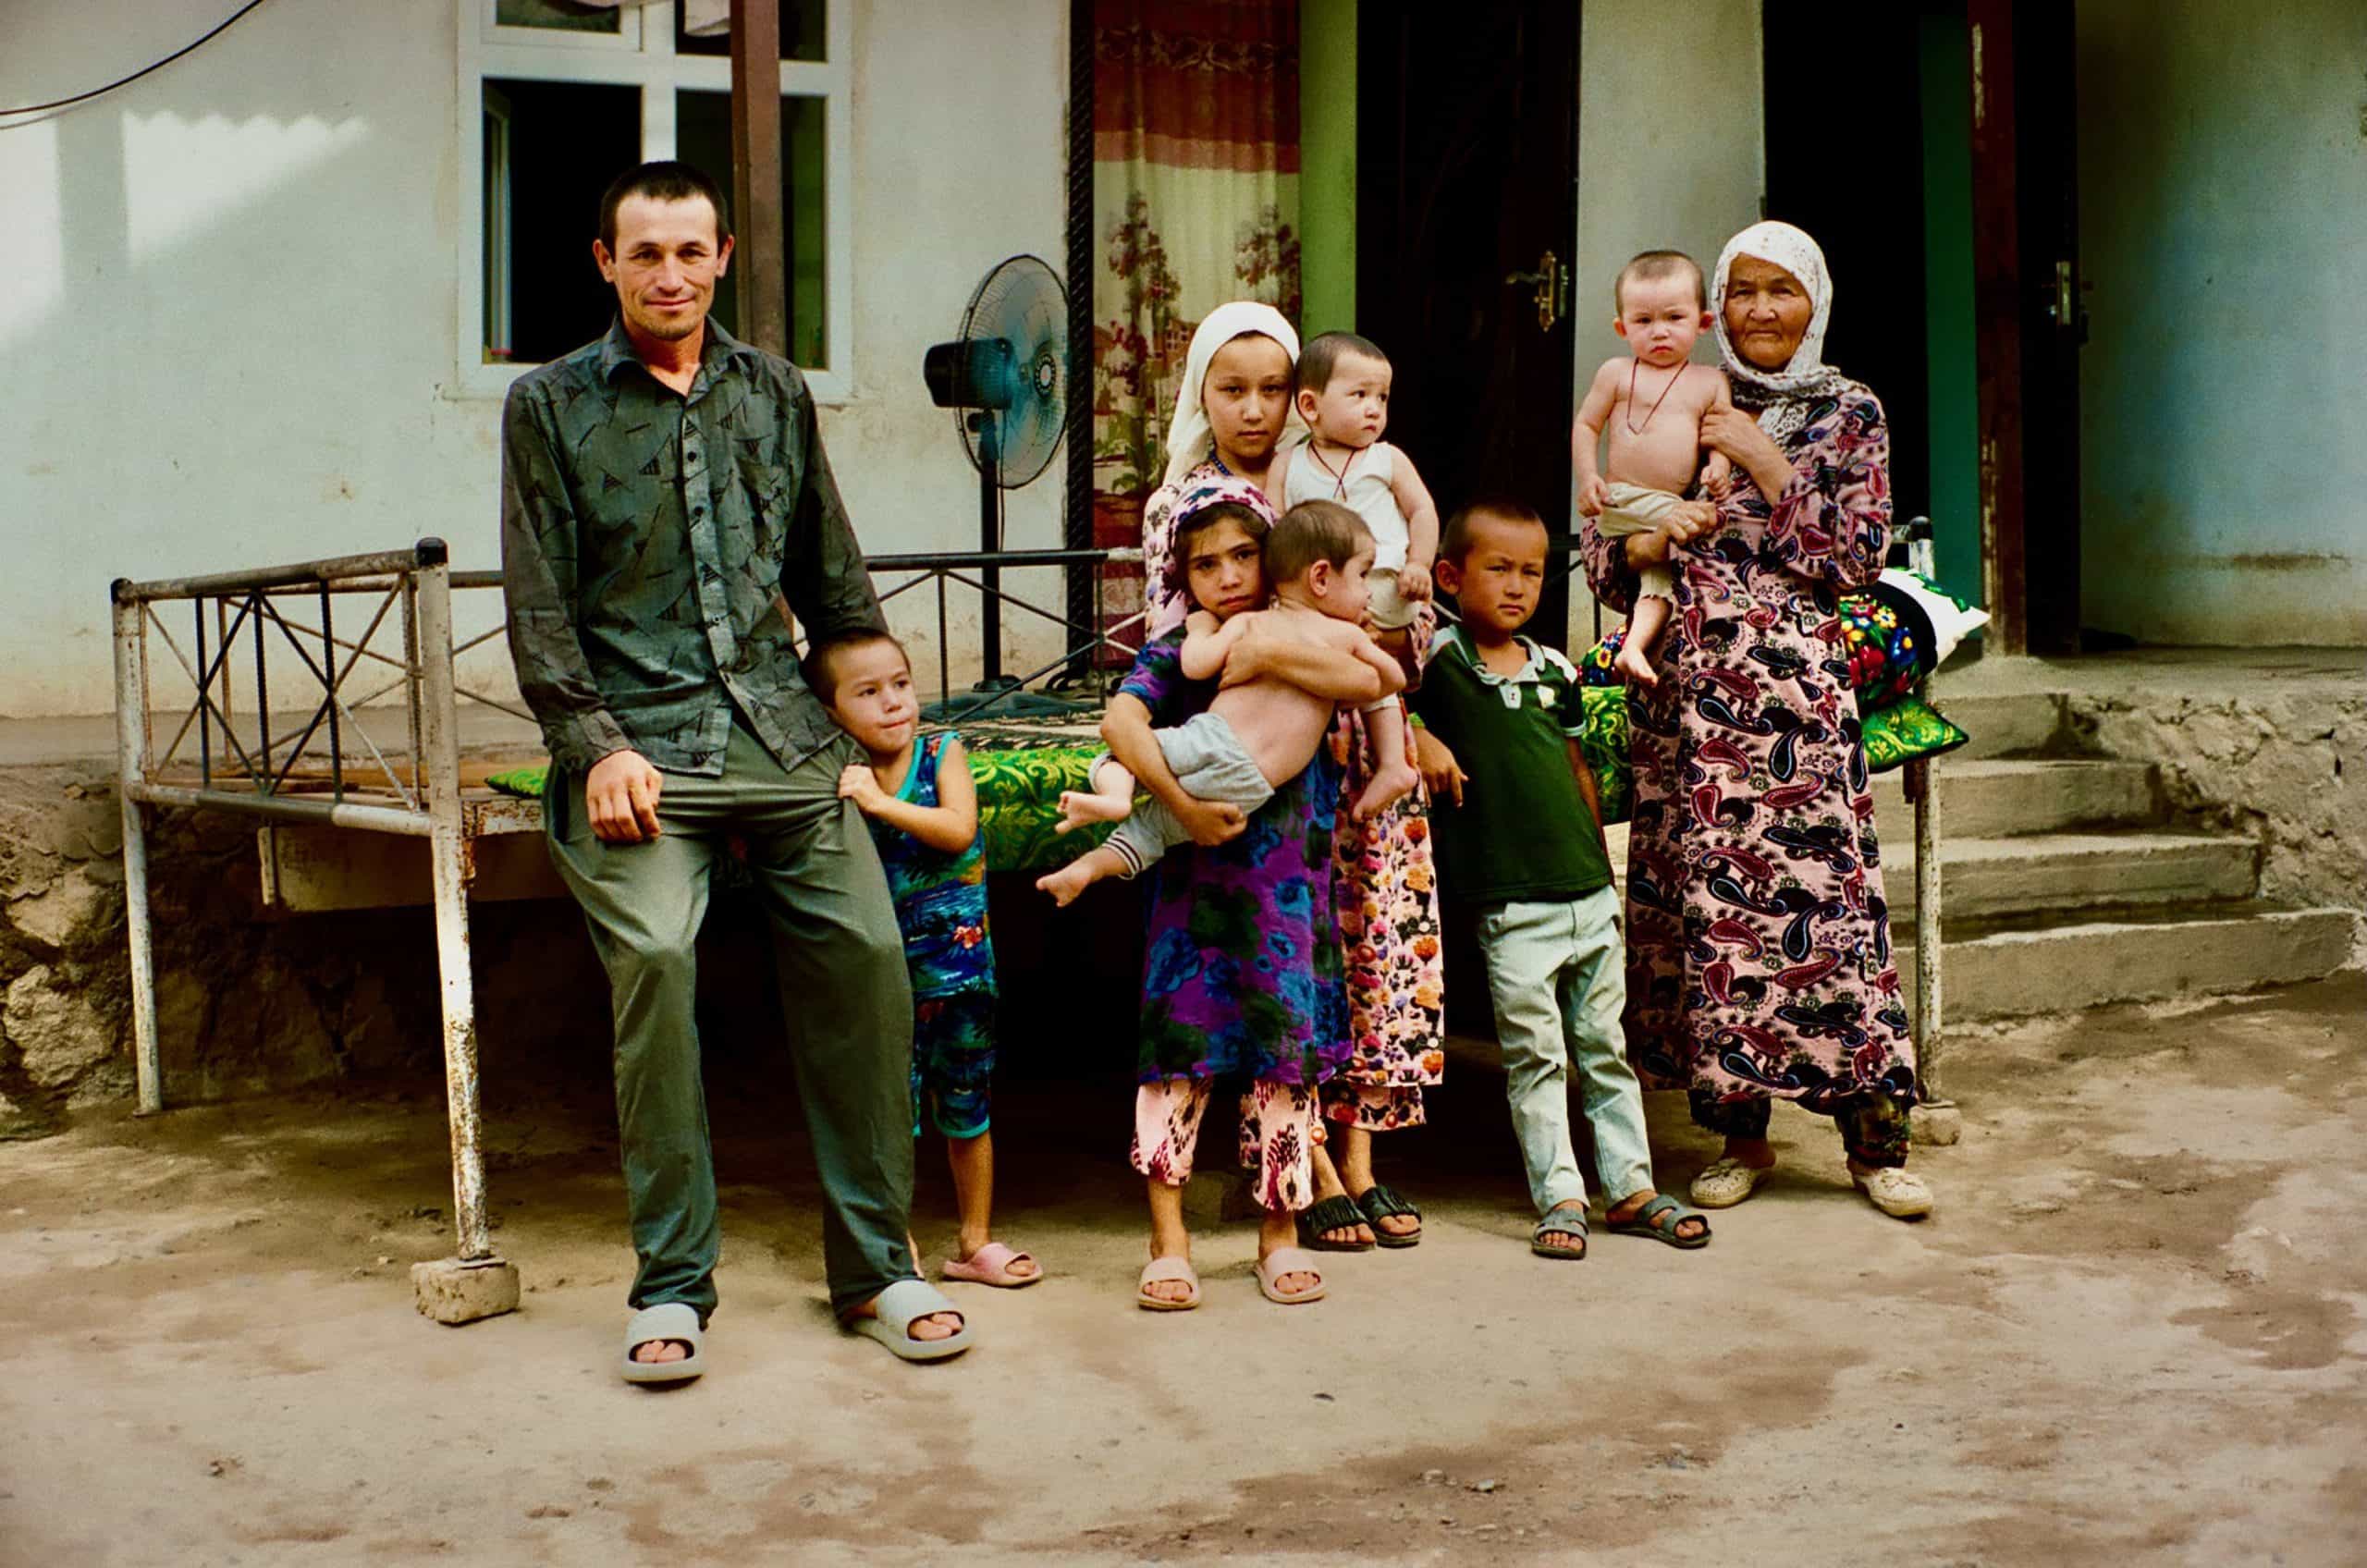
At the far right of the photo stands Dilafruz (Name changed, not the real name) , a long-time client of Humo, Gojo’s group company in Tajikistan. Born near Dushanbe, she moved to her current village after marriage, where she has since built her life and family. Today, her household is large and lively, consisting of her husband, three sons, three daughters, and seven grandchildren. It is a home filled with stories of migration, resilience, and the bonds that hold families together across borders.

Two of Dilafruz’s sons currently work in Russia as migrant labourers, while two of her daughters are married and living in other households. The sons working abroad are employed in factories, returning only once a year. August is a special month for the family: it is when all the children return home for one to three months. Both Dilafruz and her grandchildren eagerly look forward to this reunion every year, cherishing the short time they have together under the same roof.

The family’s migration story began early. All of her sons started working abroad when they were just 16 years old, back in 2012. At the time, employment opportunities in the village were scarce, and her husband was also working in Russia. Migrant work became the only option for them to sustain their livelihoods. Since then, the sons have sent remittances home every week, forming the backbone of the family’s income. Although her sons report that finding work in Russia is still relatively easy, they often avoid sharing the difficulties they face, not wanting to cause worry for their families back home.

Still, challenges could not be kept at bay forever. In March 2025, hardship struck the family when one of her sons was forcibly deported from Russia. The deportation was painful and unsettling, yet the family also found a silver lining: his return meant that his father and the children could finally spend time with him after years apart.

Recognising the toll of migrant labour, Dilafruz’s sons have urged their ageing father—her husband—to stop working abroad. The conditions are gruelling, and are especially harsh for someone his age. Moreover, the distance makes family life difficult; during his years away, the only contact he could maintain was through video calls. This reliance on smartphones to bridge the gap between loved ones abroad and families in Tajikistan has become a common thread in the lives of countless households across the country.

The support from Humo has been a critical lifeline. While Dilafruz’s family earns some income from raising cattle and cultivating corn, the primary source of livelihood remains the remittances sent by her sons from abroad. The family’s loan has been used for multiple purposes, including financing travel expenses to Russia and purchasing livestock. These investments, though modest, have helped the household navigate the uncertainties of migrant labour and sustain a stable foundation at home.

As another August approaches, Dilafruz is looking forward to gathering her children and grandchildren once more. For her, the month is not just a peak in remittances but a season of joy, reunion, and togetherness. No matter the challenges faced abroad, the return of family members brings warmth and comfort that money alone cannot buy.

Sign up to receive news from Gojo here.

B-Corp-Logo
20221107_gojo_symbol-01 (1)